What is the market overview and scope of the White Cement Market?
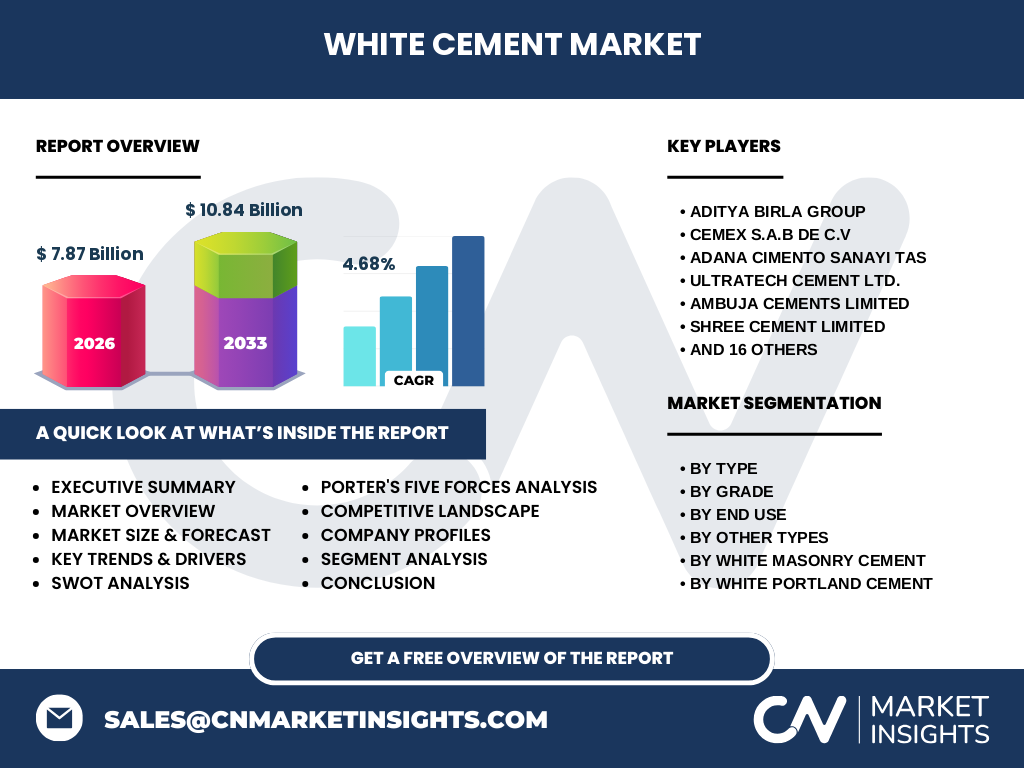
The White Cement Market is valued at 7.87 Billion in 2026, driven by high-purity limestone and low iron oxide raw materials. Our analysis indicates this aesthetic binder is critical for architectural precast, terrazzo flooring, and glass fiber reinforced concrete applications globally.
Key market drivers, restraints, challenges, and opportunities shaping White Cement Market
Growth is propelled by rising demand for solar-reflective urban surfaces and architectural aesthetics. However, energy-intensive rotary kilns and strict environmental regulations by bodies like the EPA constrain margins. Opportunities lie in developing low-carbon clinkers through alternative fuels.
Emerging trends and growth patterns in White Cement Market
The shift toward sustainable construction has accelerated adoption of blended formulations. Industry leaders are optimizing calcination temperatures and utilizing supplementary cementitious materials to reduce carbon footprints while maintaining high whiteness indices.
How did the COVID-19 pandemic impact the White Cement Market and its recovery trajectory?
Pandemic-induced supply chain disruptions and labor shortages temporarily stalled luxury real estate and commercial projects. Recovery has been robust, led by government stimulus in infrastructure and a rebound in architectural precast manufacturing across North America and Asia.
Competitive benchmarking and strategic dynamics in the White Cement Market
The landscape features intense competition among key producers such as Cemex S.A.B De C.V., Cementir Holding SPA, and Ultratech Cement Ltd. Market concentration is high in specific regions, prompting major players to secure proprietary limestone quarries and expand export terminals.
Executive summary of key findings for the White Cement Market
Our research forecasts the market to reach 10.84 Billion by 2033, expanding at a CAGR of 4.68% from 2027. Urbanization and aesthetic building trends remain the primary catalysts, favoring vertically integrated manufacturers with robust distribution networks.
Market forecast and growth projections from 2027 to 2033
Driven by sustained demand in commercial flooring and precast facades, the sector will scale from its 2026 baseline to 10.84 Billion by 2033. This trajectory reflects a steady 4.68% CAGR, underpinned by rising infrastructure investments in emerging economies.
Segmentation analysis of the White Cement Market across types, grades, and end uses
Segmentation includes: By Type: White Portland Cement, White Masonry Cement, White Portland Limestone Cement (PLC), and Other Types. By Grade: Type I, Type III, and Other Grades. By End Use: Residential, Commercial, and Industrial applications.
Regional market analysis and geographic performance distribution
Geographic performance varies significantly due to raw material availability and local building codes. The Middle East and Europe show high consumption in decorative infrastructure, while Asia-Pacific represents the fastest-growing frontier driven by rapid urbanization and commercial expansion.
In-depth regional review of key geographic markets
Middle Eastern producers like Saudi White Cement Company and Shargh White Co leverage abundant local fuel and limestone reserves. Meanwhile, European markets focus on stringent emissions compliance, driving demand for specialized low-carbon white limestone formulations.
Strategic company profiles in the White Cement Market
Industry giants like Aditya Birla Group, JK Cement Ltd., and HeidelbergCement AG dominate through technological innovation and geographic diversification. Regional players such as Cimsa Cement Industry and Trade Inc. maintain strong footholds via specialized export logistics.
Porter's Five Forces analysis of competitive pressures
Bargaining power of buyers is moderate due to specialized aesthetic requirements. Threat of substitutes is low because grey cement cannot match whiteness standards. High capital expenditure for specialized kilns creates significant barriers to entry for new market participants.
SWOT analysis highlighting strategic positioning in the industry
Strengths include superior architectural versatility and high compressive strength. Weaknesses involve high energy consumption during production. Opportunities emerge in eco-friendly binders, while threats stem from volatile energy costs and stringent environmental mandates.
Value chain analysis from raw materials to end-users
The value chain starts with the extraction of low-iron limestone and high-purity kaolin. This flows through energy-intensive calcination in specialized kilns, followed by fine grinding, bagging, and distribution via maritime ports to precast plants and construction sites.
Investment insights and high-potential areas for stakeholders
Investors should target manufacturers investing in waste-heat recovery systems and alternative raw material sourcing. High-performance White Portland Limestone Cement (PLC) segments offer lucrative expansion opportunities amid tightening carbon regulations.
Conclusion and key strategic takeaways for industry stakeholders
The White Cement Market offers robust growth potential, projected to hit 10.84 Billion by 2033. Success requires balancing aesthetic performance with aggressive decarbonization strategies to navigate tightening global environmental regulations effectively.
Research methodology detailing data triangulation and analytical modeling
Baseline estimates are triangulated by combining maritime trade registry data, primary stakeholder interviews with C-level executives, and secondary macroeconomic indicators from global construction associations to ensure rigorous market sizing accuracy.
Scope of the report, coverage parameters, and analytical limitations
This report covers global revenue estimations from 2026 to 2033, segmented by type, grade, and end-use application. Limitations include unforeseen macroeconomic policy shifts and localized trade tariff fluctuations impacting raw material supply chains.
Recent developments, corporate announcements, and strategic moves
Recent industry activity highlights capacity expansions by firms like Ambuja Cements Limited and strategic export partnerships forged by Royal White Cement Inc. Companies are actively investing in proprietary grinding technologies to enhance product whiteness and reduce emissions.